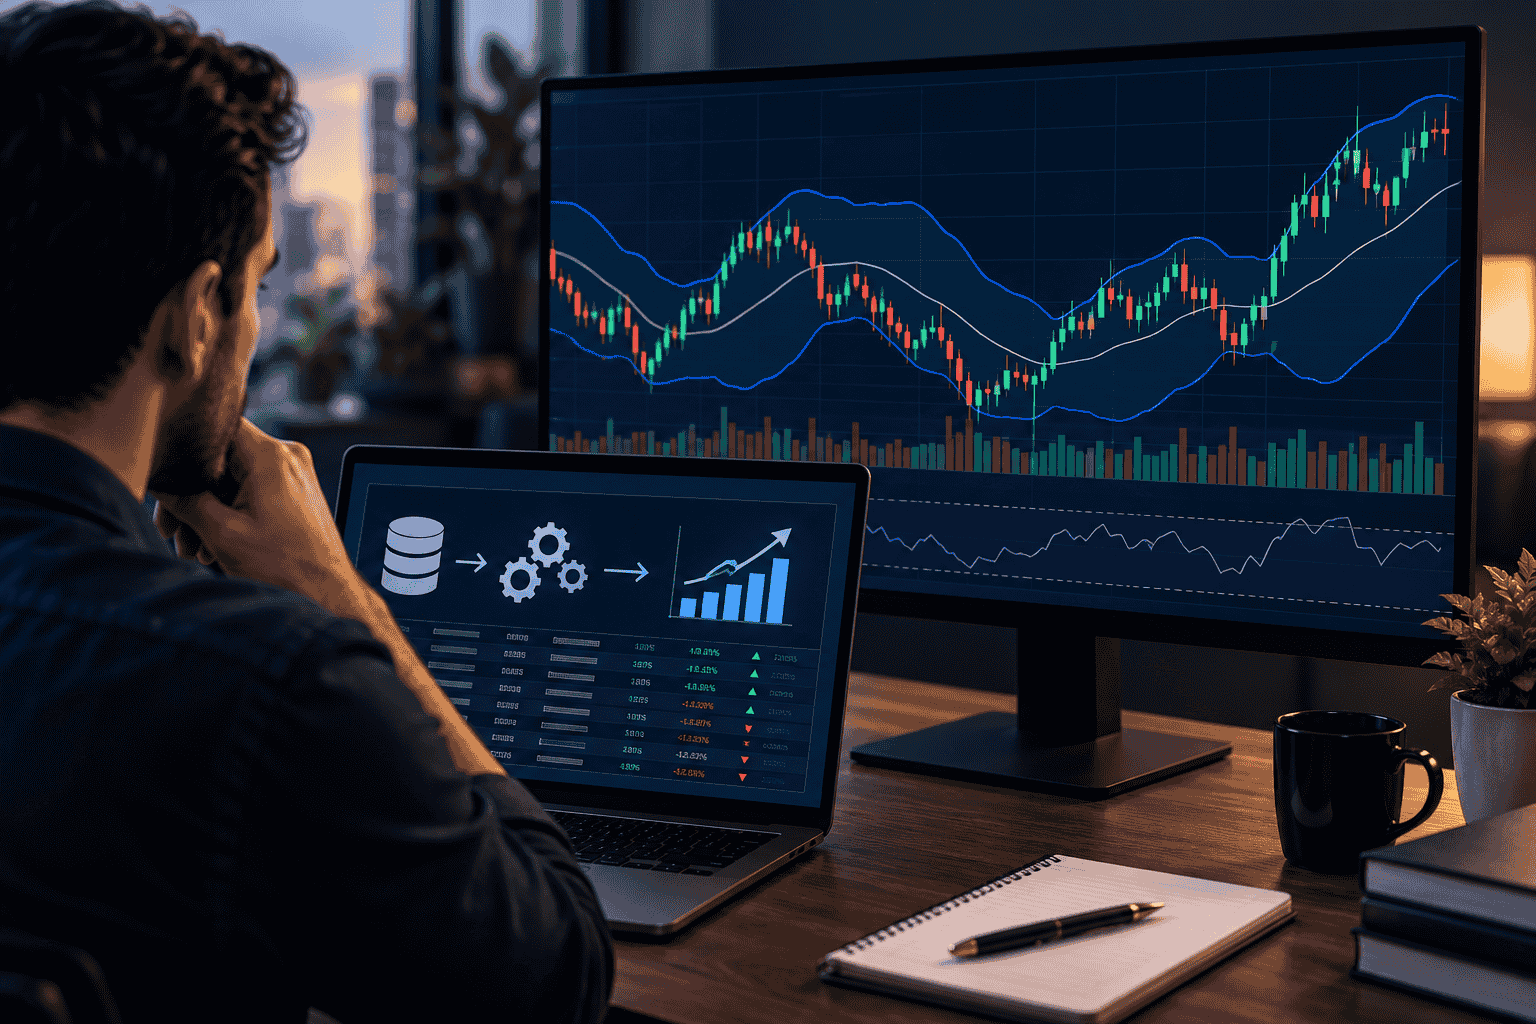
A trading strategy may look impressive on a chart, but visual inspection alone cannot tell you whether the strategy has a genuine statistical advantage. This is why learning how to backtest a Bollinger Band strategy is important for traders who want to move from subjective chart reading toward a more systematic trading process.
A Bollinger Bands backtest allows traders to apply clearly defined entry and exit rules to historical market data and study how those rules would have performed in the past. Rather than selecting a few successful examples from a chart, backtesting examines hundreds or even thousands of historical trading opportunities.
Bollinger Bands are particularly useful for backtesting because they can support several different trading concepts, including mean reversion, volatility expansion, trend continuation, breakouts, and the popular Bollinger Band squeeze strategy.
However, successful backtesting requires much more than calculating a win rate. Traders should also examine profitability, risk, drawdown, transaction costs, trade frequency, market conditions, and whether the strategy continues to perform on data that was not used to develop it.
This guide explains how to build, test, evaluate, and improve a Bollinger Band trading system without relying on hindsight.
What Are Bollinger Bands?
Bollinger Bands are a technical analysis indicator designed to measure the relative position of price and changing market volatility.
The standard Bollinger Bands setup uses a 20-period simple moving average as the middle band. The upper band is generally calculated two standard deviations above the moving average, while the lower band is calculated two standard deviations below it.
Because standard deviation changes with market volatility, the distance between the upper and lower bands expands and contracts dynamically.
When volatility increases, the bands usually widen. When volatility decreases, the bands contract. Traders can therefore use Bollinger Bands to study both price location and volatility conditions.
The traditional Bollinger Bands 20,2 settings are widely used, but backtesting allows traders to determine whether those settings are appropriate for a particular market, timeframe, or trading strategy.
Why Backtest a Bollinger Bands Strategy?
A backtesting trading strategy process answers an important question: if exactly the same trading rules had been followed historically, what would have happened?
Without backtesting, a trader may notice that prices frequently rebound after touching the lower Bollinger Band and conclude that buying the lower band is profitable. The problem is that human observation tends to remember successful examples more easily than failed ones.
During strong downtrends, for example, price may repeatedly move along the lower Bollinger Band instead of reversing. Similarly, price touching the upper band does not automatically mean that a market is overbought and about to decline.
A structured Bollinger Bands strategy backtest converts these visual assumptions into objective rules.
Instead of saying, “Buy when price looks oversold,” the strategy might say, “Enter long when the closing price moves below the lower Bollinger Band and subsequently closes back inside the bands.”
This rule can be tested consistently across historical data.
Backtesting can reveal the strategy’s win rate, average profit, average loss, profit factor, maximum drawdown, number of trades, average holding period, and performance during different market environments.
Define the Bollinger Band Strategy Before Backtesting
One of the biggest mistakes traders make is beginning a backtest without clearly defining the strategy.
Every trading decision should ideally have an objective rule.
A proper Bollinger Band trading strategy should define the indicator settings, entry conditions, exit conditions, stop-loss methodology, position sizing, transaction costs, trading timeframe, and market being tested.
For example, imagine a simple mean-reversion system using Bollinger Bands.
The strategy uses a 20-period moving average with bands positioned two standard deviations above and below the average. A long setup occurs when price closes below the lower Bollinger Band. Entry occurs when the next candle closes back above the lower band. The position is closed when price reaches the middle Bollinger Band.
That represents a much more testable strategy than simply saying “buy near the lower band.”
The clearer the trading rules, the more reliable the backtesting process becomes.
Backtesting a Bollinger Band Mean-Reversion Strategy
One of the most popular ways to use Bollinger Bands is through mean reversion trading.
Mean reversion is based on the idea that prices sometimes move temporarily away from their average before returning toward it.
The middle Bollinger Band represents a moving average, while the outer bands show how far price has moved relative to recent volatility.
A simple Bollinger Band mean-reversion strategy may look for a close below the lower band followed by a recovery back inside the bands.
The backtest could enter a long trade after that recovery and use the middle band as the profit target.
For short trades, the opposite logic could apply. Price first closes above the upper Bollinger Band and then moves back below it. A short position is entered with the middle band acting as the potential target.
Testing this strategy across different market environments is essential because mean-reversion strategies can perform differently during sideways and strongly trending markets.
A strategy that works well in a range may suffer substantial losses when a powerful trend develops.
Backtesting a Bollinger Band Breakout Strategy
Bollinger Bands can also be used for momentum and breakout trading.
A Bollinger Band breakout strategy attempts to capture price expansion rather than price reversal.
For example, a trader might enter a long position when price closes above the upper Bollinger Band while volume is above its recent average. A short position might be taken when price closes below the lower band with similar confirmation.
The assumption behind this strategy is very different from mean reversion.
Instead of expecting price to return toward the middle band, the trader assumes that movement beyond an outer band could represent increasing momentum.
The backtest should therefore measure whether Bollinger Band breakouts historically produced enough follow-through to compensate for failed breakouts.
Exit rules could include a fixed percentage stop, Average True Range stop, moving average exit, middle Bollinger Band exit, trailing stop, or risk-to-reward target.
Different exits can dramatically affect the results, which is why each variation should be tested separately.
How to Backtest a Bollinger Band Squeeze Strategy
Another widely researched approach is the Bollinger Band squeeze strategy.
The squeeze occurs when volatility decreases and the upper and lower Bollinger Bands move closer together.
Rather than treating narrow bands as a directional prediction, traders generally use the squeeze as a sign that the market has entered a period of relatively low volatility.
The important part of a Bollinger squeeze trading strategy is determining what happens after volatility begins expanding again.
One backtesting method is to calculate Bollinger BandWidth and identify periods when BandWidth reaches unusually low levels compared with its recent history.
The strategy can then wait for price to break above resistance or the upper Bollinger Band for a potential long trade. A downside breakout may trigger a short trade.
The backtest should determine whether these post-squeeze breakouts generated sufficient returns after false breakouts, slippage, and transaction costs are included.
Choose the Right Historical Data
The quality of the historical data directly affects the quality of a Bollinger Bands backtest.
For swing trading strategies, daily price data may be sufficient. For intraday strategies, traders may require hourly, 15-minute, five-minute, or even lower timeframe data.
Historical data should ideally include open, high, low, close, and volume information.
The backtest period also matters.
Testing a strategy over only a few months can produce misleading results because the market may have experienced only one type of environment.
A more robust backtest should ideally include different conditions such as bull markets, bear markets, sideways markets, high-volatility periods, and low-volatility environments.
This helps determine whether the strategy has broad usefulness or works only under specific market conditions.
Calculate Bollinger Bands Correctly
Consistency in indicator calculation is essential.
The middle Bollinger Band is typically a 20-period simple moving average.
The upper band is calculated using the moving average plus a multiple of standard deviation, while the lower band is calculated using the moving average minus that same volatility adjustment.
With the standard settings, that multiplier is normally two.
Changing the moving average period or standard deviation multiplier changes the behavior of the indicator.
For example, narrower bands may generate more trading signals but could also produce more false signals. Wider bands may generate fewer signals but potentially identify more extreme price movements.
A Bollinger Bands strategy backtest can help traders evaluate these differences objectively.
Include Transaction Costs and Slippage
A backtest can look highly profitable before trading costs and considerably weaker afterward.
This is particularly important for strategies that generate many trades.
Brokerage fees, exchange charges, bid-ask spreads, taxes where applicable, and slippage should therefore be incorporated into realistic backtesting assumptions.
Slippage represents the difference between the theoretical price at which the model expects to trade and the price that might realistically be available.
Suppose a Bollinger Bands strategy generates a small average profit per trade but trades very frequently. Transaction costs could eliminate a substantial portion of that theoretical advantage.
Realistic costs help prevent a paper strategy from appearing more attractive than it would be in actual trading.
Measure the Bollinger Bands Strategy Win Rate
The Bollinger Bands strategy win rate is one of the first statistics traders usually examine, but it should never be evaluated alone.
Win rate simply measures the percentage of trades that generated a profit.
A strategy can have a high win rate and still lose money if losing trades are significantly larger than winning trades.
Conversely, a breakout system may have a relatively low win rate but remain profitable because successful trades are much larger than losing trades.
The relationship between win rate and payoff ratio is therefore more important than either statistic individually.
Calculate Profit Factor
Profit factor is another useful metric when evaluating a Bollinger Band backtest.
Profit factor compares the total profits generated by winning trades with the total losses generated by losing trades.
A profit factor above 1 indicates that historical gross profits exceeded historical gross losses.
However, traders should avoid assuming that a high profit factor automatically means that a strategy will perform similarly in the future.
Sample size matters significantly.
A strategy showing excellent results from 15 trades provides much less evidence than one demonstrating reasonably consistent behavior across hundreds of trades and multiple market environments.
Measure Maximum Drawdown
A strategy’s total return tells only part of the story.
Maximum drawdown measures the largest historical decline from an equity peak to a subsequent trough.
This is one of the most important measures of trading risk.
Imagine two Bollinger Bands strategies generating similar historical returns. Strategy A experiences a maximum drawdown of 10%, while Strategy B experiences a drawdown of 40%.
Even if their final returns are similar, their risk profiles are clearly very different.
Drawdown analysis can help traders decide whether the strategy is financially and psychologically realistic.
Evaluate the Sharpe Ratio and Risk-Adjusted Returns
Another useful performance measurement is the Sharpe ratio, which evaluates return relative to volatility.
Rather than focusing entirely on how much money a strategy generated, risk-adjusted metrics attempt to determine how efficiently those returns were produced.
Other useful backtest measurements include expectancy, average return per trade, average winning trade, average losing trade, consecutive losses, recovery factor, trade duration, and exposure.
A strong evaluation combines several statistics rather than selecting whichever metric makes the strategy appear most attractive.
Avoid Look-Ahead Bias
One of the most dangerous backtesting errors is look-ahead bias.
Look-ahead bias occurs when a strategy unintentionally uses information that would not have been known at the moment the historical trade was supposedly taken.
For example, entering a trade at today’s opening price based on today’s final closing price would be impossible in real trading because the close had not yet occurred at the open.
The backtest should therefore respect the actual sequence in which market information becomes available.
If a strategy requires a candle to close before confirming a signal, the theoretical trade should normally occur only after that confirmation becomes available.
Avoid Overfitting the Strategy
Another common problem is overfitting.
Overfitting occurs when traders repeatedly modify parameters until the system fits historical data extremely well.
For example, a trader might test dozens of moving average lengths, standard deviation settings, stop-loss values, profit targets, and confirmation indicators.
Eventually, one particular combination may produce exceptional historical performance purely by chance.
Instead of discovering a genuine market relationship, the trader may simply have discovered parameters that happen to fit past noise.
This is why simpler strategies and independent validation are generally preferable.
Use In-Sample and Out-of-Sample Testing
A more robust trading strategy backtest divides historical data into separate periods.
The in-sample period is used to develop the trading rules.
The out-of-sample period is then used to evaluate those rules on data that was not used to design the strategy.
Suppose historical data from 2010 through 2022 is used to develop a Bollinger Band system. Data from 2023 onward could then be reserved for independent testing.
If performance collapses during the unseen period, the original results may have been caused by overfitting.
If similar characteristics continue to appear, confidence in the model may increase, although no historical test can guarantee future performance.
Use Walk-Forward Testing
Walk-forward analysis takes validation further.
Instead of using only one training period and one testing period, the model moves through several consecutive historical windows.
Parameters are developed using one period and evaluated during the next period. The process then moves forward and repeats.
Walk-forward testing can help determine whether the Bollinger Bands trading strategy remains reasonably stable as market conditions change.
A strategy that performs only when optimized against one historical period may have limited practical value.
Test the Strategy Across Different Markets
A useful strategy should also be examined across more than one instrument whenever appropriate.
A Bollinger Band strategy could be tested on stocks, stock indices, commodities, forex markets, futures, or cryptocurrencies.
Different assets have different volatility characteristics, trading hours, liquidity conditions, and trend behavior.
A strategy working well on the S&P 500 may behave differently on Bitcoin, gold, Nifty 50, or an individual stock.
Cross-market testing can help determine whether the strategy reflects a broader market principle or a temporary feature of one instrument.
Backtesting Bollinger Bands in TradingView
One accessible method is a TradingView Bollinger Bands backtest.
TradingView allows traders to create systematic strategies using Pine Script and evaluate historical results through its Strategy Tester.
A trader can program Bollinger Bands entry rules, exits, stop losses, position sizing, commissions, and other conditions.
TradingView can then generate information such as net profit, number of trades, percentage of profitable trades, drawdown, and other performance statistics.
The advantage of automated testing is consistency. Once the strategy has been coded correctly, the same rules can be applied throughout the dataset without subjective interpretation.
Backtesting Bollinger Bands With Python
More advanced traders and quantitative researchers may prefer a Bollinger Bands Python backtest.
Python allows large datasets to be analyzed using tools designed for data analysis and quantitative research.
A Python backtest can calculate Bollinger Bands, identify entry conditions, simulate trades, calculate transaction costs, track portfolio equity, and produce detailed performance statistics.
Python also makes it easier to perform parameter testing, out-of-sample analysis, walk-forward testing, Monte Carlo analysis, and cross-market comparisons.
However, flexibility creates another risk: it becomes easy to test hundreds or thousands of combinations until an apparently exceptional strategy appears.
The objective should be to test a logical hypothesis rather than search indefinitely for whichever settings produced the highest historical return.
How to Improve a Bollinger Bands Strategy
Once the basic system has been tested, traders can examine whether additional conditions improve its behavior.
For example, a Bollinger Band mean-reversion system could include RSI confirmation to avoid entering every outer-band touch.
A breakout strategy might use trading volume to confirm price movement.
A trend filter such as the 50-day or 200-day moving average could restrict long trades to broader uptrends and short trades to broader downtrends.
ATR may be used for volatility-adjusted stop losses.
However, every additional indicator increases strategy complexity.
The key question should not simply be whether adding another condition improves historical performance. Traders should consider whether there is a reasonable market explanation for why the condition might improve the strategy.
Common Bollinger Bands Backtesting Mistakes
One major mistake is assuming that every touch of an outer Bollinger Band represents a reversal.
Price can remain near the upper band during strong bullish trends and near the lower band during strong bearish trends.
Another mistake is optimizing settings excessively. Testing hundreds of parameter combinations dramatically increases the probability of finding attractive historical results by chance.
Ignoring commissions and slippage can also make high-frequency strategies appear artificially profitable.
Using too little historical data, ignoring delisted securities, incorrectly handling missing data, and relying exclusively on a win rate can create additional distortions.
A reliable backtesting process should attempt to make historical simulation more difficult and realistic rather than searching for assumptions that make the performance look better.
Is a Bollinger Bands Strategy Profitable?
There is no universal answer.
The profitability of a Bollinger Bands trading strategy depends on the strategy rules, asset, timeframe, transaction costs, execution method, risk management, and market environment.
Bollinger Bands themselves do not automatically create an edge.
They provide a framework for measuring price relative to an average and observing changes in volatility.
The trading hypothesis built around those measurements is what must be tested.
A mean-reversion Bollinger strategy, a squeeze strategy, and a momentum breakout strategy can generate completely different results despite using the same indicator.
Final Thoughts on How to Backtest a Bollinger Band Strategy
Learning how to backtest a Bollinger Band strategy is ultimately about replacing assumptions with evidence.
Start with a clear hypothesis. Define exact Bollinger Bands settings, entry rules, exits, risk controls, transaction costs, and position sizing before analyzing the results.
Then evaluate the strategy using more than total return. Study win rate, payoff ratio, profit factor, maximum drawdown, Sharpe ratio, expectancy, trade frequency, and performance under different market conditions.
Most importantly, separate strategy development from strategy validation. Use out-of-sample data, walk-forward analysis, different securities, and realistic trading costs to determine whether the results remain reasonably stable.
A visually attractive strategy is easy to find on a historical chart. A repeatable trading system requires much more evidence.
Backtesting does not prove that a Bollinger Bands strategy will make money in the future. What it can do is help traders understand how a clearly defined strategy behaved historically, identify weaknesses, compare alternative rules, and make trading decisions through a more disciplined and data-driven framework.